Cost Segregation Studies for Skilled Nursing Facility Buildings
Cost segregation reclassifies SNF assets into faster depreciation schedules, freeing cash sooner.
Cost segregation studies for skilled nursing facility buildings address a costly mismatch between long tax recovery periods and short-lived clinical assets. Their value comes from moving supported costs into the right depreciation categories. For SNF owners, dense specialized infrastructure and restored 100% bonus depreciation make that timing opportunity especially valuable, provided the ownership structure, tax position, and engineering evidence support it.
Why SNF buildings carry a structural depreciation disadvantage
Skilled nursing facilities are classified as nonresidential commercial property and depreciate over 39 years, rather than the 27.5-year schedule available to residential housing. A building’s use as a place where people live does not give it residential tax treatment. The distinction slows cost recovery from the outset. For an owner with substantial capital tied up in a facility, the default schedule spreads deductions over a period that bears little relationship to the replacement cycles of many assets inside it.
Consider a $20 million facility with its full cost on the 39-year schedule. Its depreciation treats the building cost as one long-lived whole, even though the facility contains components that age or become obsolete much sooner. Clinical technology does not age like a shell. Nurse call systems, specialized wiring, emergency infrastructure, and accessible fixtures do different jobs from the structure itself. Because SNFs contain so much of this infrastructure, their mismatch between tax recovery and functional life is unusually pronounced.
How cost segregation corrects the mismatch between tax schedule and physical reality
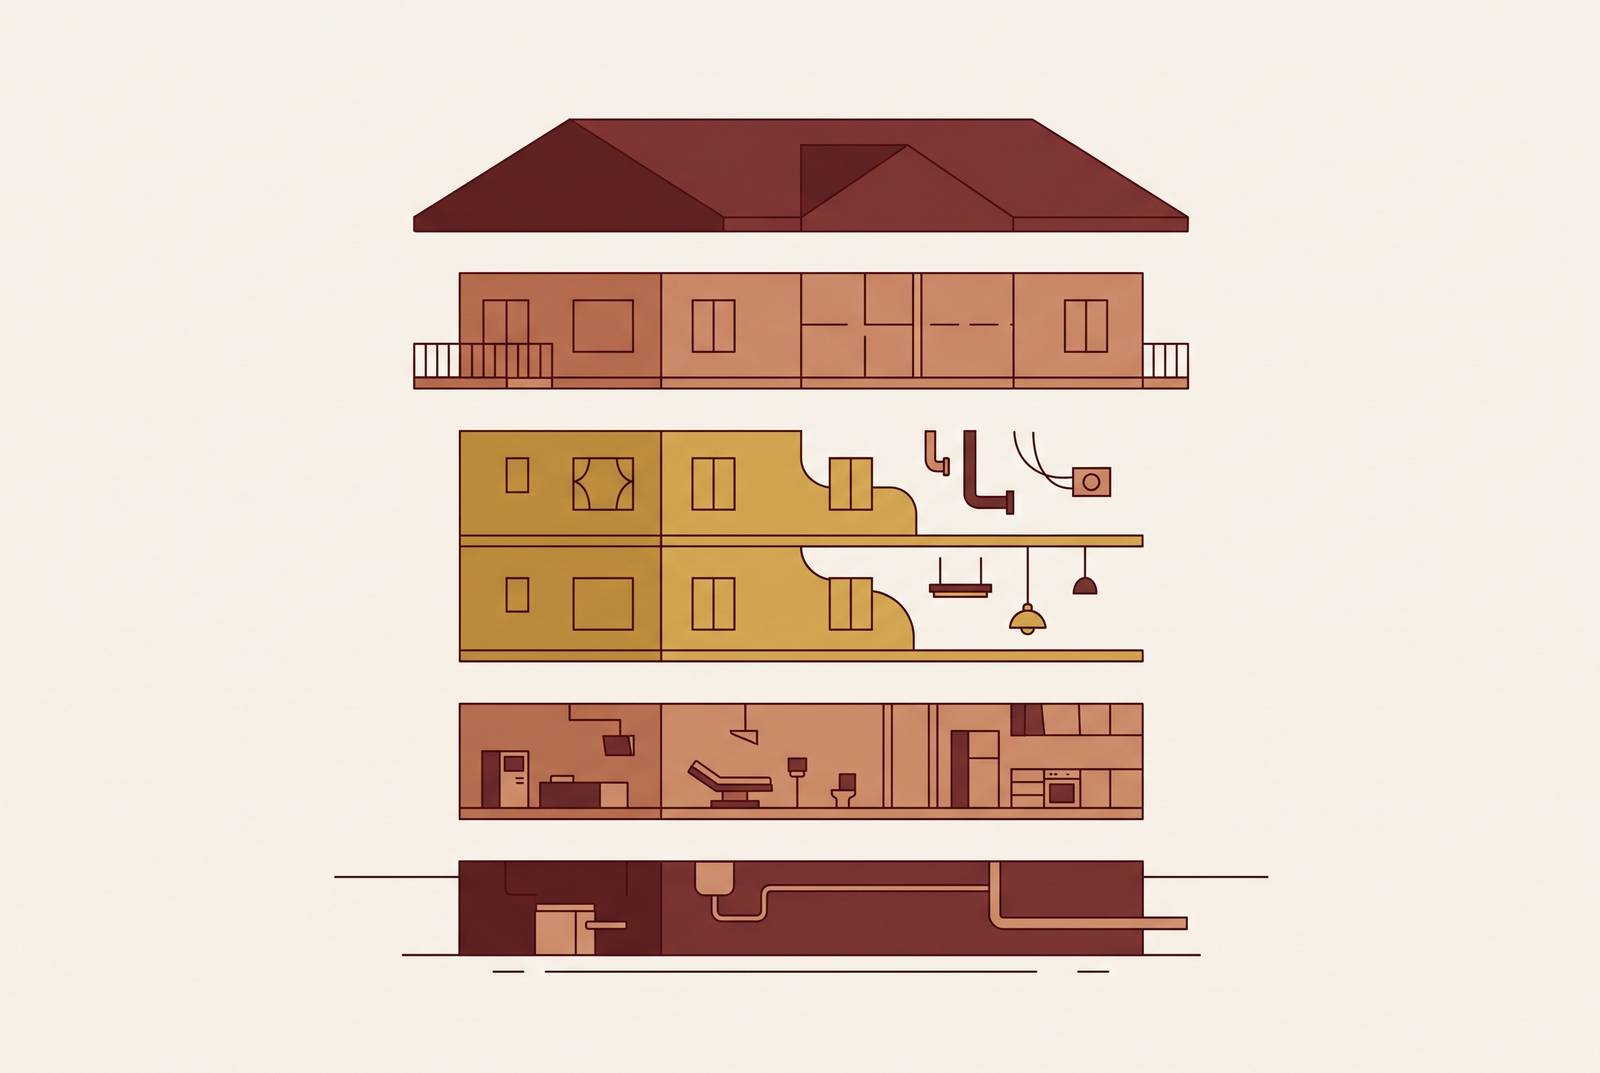
A cost segregation study separates costs that belong to shorter-life assets from costs that belong to the building structure. Under IRC §168, the tax depreciation system allows supported costs to be reclassified from 39 years into 5-, 7-, or 15-year recovery periods. The study brings deductions for existing costs forward so the owner gets the time-value benefit of tax savings sooner.
A defensible study combines tax analysis with engineering work to establish what the property contains, what each asset does, and which costs belong to it. Construction invoices and building plans are the documents on which the study is based. An on-site inspection, including exterior and interior photographs, adds facts that those documents may not show.
Indirect, or soft, construction costs must be assigned to the appropriate assets, a step that a document-only review can overlook. The final report brings those allocations and their support together in a form usable for tax planning and IRS documentation.
Which SNF-specific assets qualify for accelerated treatment
Inside an SNF, the clinical and hospitality layers create a concentration of potentially reclassifiable costs beyond what a standard office building or warehouse generally offers. The clinical layer includes nurse call systems and their monitoring wiring, medical gas piping and outlet connections, and medical-grade electrical wiring that differs from standard building electrical. Function is the central distinction in this analysis. Dedicated and emergency power systems, emergency response equipment, and specialty ventilation designed for infection control or clinical environments also belong in the study’s assessment. These systems typically reclassify to 5- and 7-year lives where the facts support that treatment.
Nurse call technology shows this mismatch clearly. A system can become functionally obsolete in a short time while its cost is still being recovered on the default 39-year schedule. The analysis must tell specialized infrastructure apart from the systems that serve the building as a whole. That distinction connects the recognizable asset in the facility to the tax treatment claimed for it.
Accessible fixtures and accessibility modifications, specialty lighting, individual unit finishes, commercial kitchen equipment, removable flooring and fixtures, and procedure-room casework and finishes are all relevant categories. Surface parking and landscaping can be treated as 15-year site improvements. Taken together, these categories explain why an SNF study examines the whole property rather than stopping at obvious medical equipment.
Why the OBBBA's restoration of 100% bonus depreciation sharpens the case for acting now
The One Big Beautiful Bill Act, or OBBBA, signed July 4, 2025, permanently restored 100% bonus depreciation for qualifying property acquired after January 19, 2025, with no scheduled phase-down. That change reversed the TCJA trajectory, which would have reduced the rate to a fraction of full expensing by 2026 and eliminated it by 2027. The gap between partial-rate and full expensing is substantial. Instead of deducting only part of an eligible asset’s cost immediately and recovering the balance later, an owner can expense the full qualifying cost in the first year.
IRS Notice 2026-11, issued January 14, 2026, provides interim guidance that property acquired and placed in service after January 19, 2025, qualifies for the restored treatment under IRC §168(k). The shorter-life components identified through cost segregation are the assets that can qualify for bonus depreciation, so classification and immediate expensing work together.
Bonus depreciation also has no phaseout limits, a significant feature for SNFs with substantial depreciable bases. A large qualifying allocation is not curtailed merely by the size of the property investment. The reason to act sooner is therefore not an approaching scheduled phase-down under the restored law. It is the opportunity to bring qualifying deductions into the first tax year rather than leave costs spread across longer recovery periods, subject to the owner’s ability to use them.
How margin pressure in the SNF sector makes accelerated depreciation a cash-flow lever, not just a tax strategy
SNF reimbursement and operating costs do not move in tandem, making the gap between them a persistent financial constraint. MedPAC’s March 2026 report found that, from 2023 through 2024, Medicare payments per day to freestanding SNFs grew about twice as fast as costs per day. Yet the all-payer total margin, covering all payers and lines of business, improved only from 0.4 percent in 2023 to 2.1 percent in 2024. Favorable Medicare movement did not produce broad financial relief. The same report cautioned that complex third-party arrangements may cause margins to be understated.
The Commission also recommended that Congress reduce 2026 Medicare base payment rates for SNFs by 4 percent for fiscal year 2027. The recommendation, which has not been enacted, shows why owners cannot plan their finances on the assumption that reimbursement will reliably work in their favor. With reimbursement uncertain, accelerated depreciation gives owners a way to increase post-tax cash without changing care delivery, staffing levels, or quality metrics. Its practical value is liquidity rather than an improvement in the underlying reimbursement model.
Tax savings that come sooner can free up cash for capital reinvestment, debt service, or working capital. Lenders and investors look at that ability to free up cash alongside operating margin when they assess SNF assets. The same report noted that price per bed has been stable since 2024 and that investors are optimistic about the HUD agency loan environment. Stronger post-tax cash flows therefore have valuation implications in a sector that continues to attract investment. The distinction remains important, however, because a tax deduction is useful only where it produces a usable tax benefit.
Who can use a cost segregation study and under what ownership structures it works best
The benefit belongs to the real estate owner. Ownership determines where the deduction can land. In a sale-leaseback, the operating entity has sold the facility and leases it from a real estate entity. Because that operator no longer holds the depreciable real property, the direct benefit of a building study belongs, if available, to the landlord.
For owner-operators, where the same entity or commonly controlled group holds the real estate and operating license, implementation is generally more straightforward and typically more valuable. Related-party arrangements nevertheless require careful reporting. An OIG audit examined whether selected SNFs disclosed related parties as required and whether related-party costs complied with Medicare requirements. The audit recommended that CMS require Medicare Administrative Contractors to check related-party cost reporting as part of their normal desk review or audit work.
A second question concerns whether the taxpayer can use the deduction now. Passive activity and at-risk rules limit the benefit, making it most immediate where sufficient income of the appropriate type is available to absorb it. Holding period also affects the economic result. Depreciation recapture under IRC §1250 and §1245 can produce income at sale, so accelerating deductions now must be weighed against potential recapture later. These conditions generally make a study more useful for long-hold and owner-operator SNFs than for properties whose owners plan to sell soon.
How look-back studies make accelerated depreciation available to facilities already in service
An earlier placed-in-service date does not exclude a facility from cost segregation. A look-back study can recover depreciation passed over in prior years without amended tax returns. The mechanism is a Form 3115 change in accounting method. It allows the taxpayer to claim the cumulative accelerated depreciation that would have been taken had the study been completed at acquisition as a single current-year §481(a) adjustment. This makes the opportunity relevant to both existing portfolios and new acquisitions.
A catch-up deduction does not automatically receive current-year 100% bonus treatment merely because the study is completed now. The underlying property’s earlier placed-in-service date remains relevant. Even where restored bonus depreciation does not apply, recovering prior-year depreciation now has a significant time-value benefit. Prior renovations and expansions may also present opportunities separate from the original acquisition. For an otherwise eligible prior-year facility, the practical question is not whether its age prevents a study, but whether that study has been done yet.
What makes a cost segregation study defensible when the IRS examines it
A study’s conclusions are only as strong as the evidence supporting them. IRS Publication 5653, the Cost Segregation Audit Techniques Guide, sets out how examiners review asset classifications and the documents that support them. A qualified provider plans the work to answer those examination questions. Invoice review alone is materially weaker than an analysis that also inspects the property, because classifications must withstand comparison with the actual building. The report must show genuine engineering analysis and retain support that can answer a request for records.
HUD 232 financing adds a separate reporting obligation. HUD’s updated Section 232 Handbook provisions, effective January 5, 2026, require annual financial statements to comply with its Uniform Financial Reporting Standards. For-profit borrowers must send in those statements within 90 calendar days of fiscal year-end. Non-profit borrowers may submit a borrower-certified statement within 90 days, with an audited statement due within nine months. Changes arising from the study must be reflected accurately in the applicable reporting rather than allowed to create inconsistencies between deliverables.
Large first-year depreciation deductions do not reduce net operating income for cash-based HUD underwriting purposes, while usable tax savings improve liquidity for the entity receiving the benefit. Ownership and reporting must remain aligned throughout. The lesson for an SNF owner is to choose a provider whose final report supplies IRS-ready documentation and whose team understands SNF financial reporting, HUD compliance, and tax strategy together. That breadth supports implementation in which a well-founded tax position also fits the facility’s financial statements and financing obligations.